Water Damage Insurance in Florida: A Guide for Boynton Beach Owners
Most Florida homeowners policies cover sudden, accidental water damage from inside the home, such as a burst supply line, but not outside flooding or leaks that went on for a long time. For Boynton Beach owners, three Florida rules matter most: the one-year claim deadline, the 2023 end of post-loss assignment of benefits, and the condo association split under F.S. 718.111. This guide explains each in plain English.
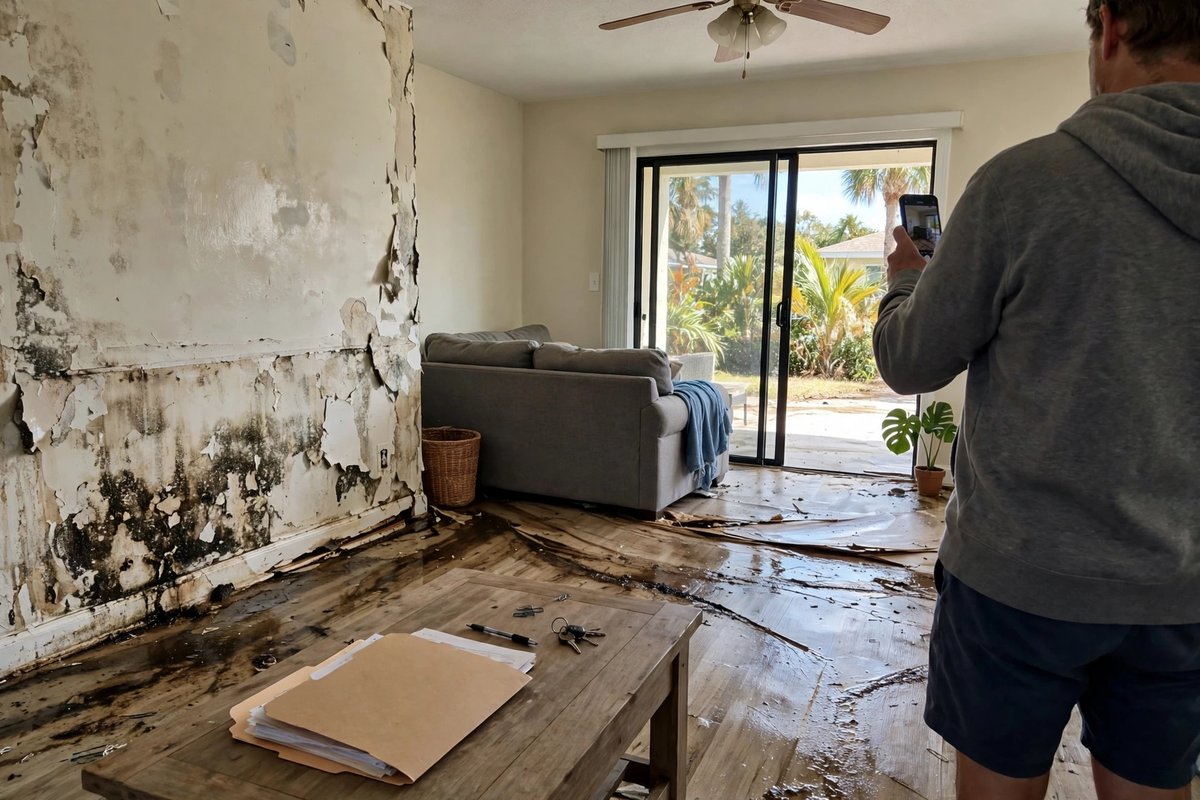
Sudden vs gradual water damage under Florida policies
This is the line most coverage decisions turn on.
| Usually treated as sudden and accidental | Usually treated as gradual, wear and tear, or excluded |
|---|---|
| A supply line or pipe that bursts | A slow drip under a sink that went on for months |
| A washing machine hose that splits | A shower pan that leaked into the wall over time |
| A water heater tank that suddenly fails | A roof that leaked repeatedly from age |
| An AC drip pan that overflows | Mold from ongoing humidity or skipped maintenance |
Many policies cover the water damage a sudden event causes, but not repairing the item that failed, such as the pipe, water heater or AC unit.
Flood, homeowners and condo policies in Florida
A new flood policy usually has a waiting period before it starts, so it can't be bought once water is rising.
| Policy | What it is mainly for | Water it usually doesn't cover |
|---|---|---|
| Homeowners (often HO-3) | Your house and belongings, including sudden internal water damage | Outside flooding, king tides, storm surge; often sewer backup without an endorsement |
| Condo unit owner (HO-6) | Your unit's interior items, upgrades and belongings | Parts of the building the association insures; outside flooding |
| Condo association master policy | The building as originally installed, under Florida Statute 718.111(11) | Owners' interior items such as floor coverings and cabinets |
| Flood (NFIP or private) | Water rising from outside: flooding, storm surge, king tides | Sudden internal leaks covered by homeowners |
Florida's claim deadlines
Under Florida Statute 627.70132:
- A new or reopened property claim must be reported to your insurer within one year of the date of loss.
- A supplemental claim must be reported within 18 months of the date of loss.
Don't wait for those limits. Reporting early makes it easier to show what happened and when, and stops the damage from growing.
What Florida's 2023 assignment of benefits ban means for you
An assignment of benefits (AOB) was a form that let a contractor take over your insurance claim and be paid directly by your insurer. Under Florida Statute 627.7152, a post-loss assignment of benefits is void for residential and commercial property policies issued on or after January 1, 2023.
What that means in practice:
- You stay in control of your claim. You deal with your insurer directly.
- Read anything you sign. A work authorization is not the same as assigning your benefits.
- Be cautious of pressure to sign forms on the spot or of promises that you will "pay nothing."
- Ask how payment works before work starts, including your deductible and what happens if the insurer pays less than the estimate.
How to document a water damage loss in Boynton Beach
Good records are the most useful thing you can bring to a claim.
- Stop the water and make the area safe.
- Photograph and video everything before cleanup: the source, every wet room, water lines on walls, and damaged belongings.
- Write down the date and time you discovered the damage.
- Keep damaged items or photograph them in detail before disposal; your insurer may want to see them.
- Keep the failed part if a plumber removes it, such as a broken hose or pipe section.
- Save every receipt for emergency repairs, drying, hotel stays and supplies.
- Ask for moisture readings and drying logs from the water damage work.
- Write down every conversation with your insurer: date, name and what was said.
Special situations in Boynton Beach
- Condos: the association's master policy and your HO-6 policy may each cover part of one leak. Notify the association in writing. See condo water damage.
- Seasonal homes: many policies limit coverage for long-running leaks or extended vacancy. Read your policy's wording before you leave. See vacant and snowbird home water damage.
- Hurricanes: many Florida policies have a separate hurricane deductible for named storms.
- King tides and flooding: generally a flood policy matter, not homeowners. See flood and king tide cleanup.
- Sewer backup: often covered only with a water or sewer backup endorsement.
- Mold: many policies cap mold coverage at a lower limit.
Getting help with a Florida water damage claim
Some homeowners handle claims themselves. Others hire help for large or disputed claims:
- A public adjuster is licensed in Florida to represent policyholders and is usually paid a percentage of the claim.
- An attorney who handles property insurance can advise on disputes and denials.
Ask about fees and licensing up front, and get any agreement in writing.
Florida water damage insurance FAQs
Is water damage covered by homeowners insurance in Florida?
Sudden, accidental water damage from inside the home, such as a burst pipe or an overflowing appliance, is often covered. Gradual leaks, wear and tear, and outside flooding usually are not. Your specific policy wording decides, so read your declarations page and coverage sections.
How long do I have to file a water damage claim in Florida?
Under Florida Statute 627.70132, a new or reopened claim must be reported within one year of the date of loss, and a supplemental claim within 18 months. Reporting sooner is better, because it is easier to document what happened.
Should I call my insurance company or a restoration company first?
Stop the water and take photos first. Then you can report the loss and arrange water removal the same day. Waiting for approval while water sits usually makes the damage worse. Keep every receipt for emergency work.
Can a restoration company bill my insurance directly in Florida?
For policies issued on or after January 1, 2023, a post-loss assignment of benefits to a contractor is void under Florida Statute 627.7152. You remain in charge of your claim. Ask any company how payment works, and read every document before signing.
Why was my water damage claim denied?
Common reasons include damage judged gradual or long-term, wear and tear, outside flooding on a homeowners policy, late reporting, or missing documentation. Ask the insurer for the denial reason in writing and which policy section it relies on. For disputes, a public adjuster or attorney can review it.
Does homeowners insurance cover mold?
Many Florida policies limit mold coverage, often with a lower cap. Mold that results from a sudden, covered water event is more likely to be covered than mold from long-term moisture. Check your policy's mold section.
This page is general information, not legal or insurance advice. Your policy wording and your insurer's decision control your coverage.
Get your Boynton Beach home dried while you sort out the claim
Most policies ask owners to take reasonable steps to keep damage from getting worse. Photograph everything, report the loss early, and keep every receipt while the water is removed and your Boynton Beach home is dried.
Boynton Beach, FL Map
Find water damage help across Boynton Beach, FL. Call (561) 264-1892 for fast help.
Get help with your water damage
Call now or send your details, and keep photos of everything.